A warm spot on the floor, a water bill that suddenly jumps, or the sound of water moving when every faucet is off can point to a leak beneath your concrete foundation. The repair itself is urgent, but many homeowners have a second concern just as quickly: does their insurance include slab leak coverage?
The honest answer is that it depends on the cause of the leak, the wording of your policy, and which part of the loss you are asking the insurer to pay for. A homeowners policy may help with certain sudden water damage, but it may not cover the failed pipe, the cost to locate it, or repairs that result from age, corrosion, or long-term wear.
What Slab Leak Coverage Usually Means
A slab leak is a leak in a water or sewer line located below the concrete foundation of a home. Because the pipe is hidden, the damage can build before there is visible water inside. Moisture can affect flooring, baseboards, drywall, cabinets, and the foundation area if the issue is left unresolved.
When homeowners ask about slab leak coverage, they are often referring to several different expenses at once. Those expenses can include leak detection, opening the slab or another access point, repairing or rerouting the pipe, drying damaged materials, and replacing flooring or walls. Insurance companies do not always treat each cost the same way.
A policy may provide coverage for resulting water damage when a pipe breaks suddenly and accidentally. For example, if a covered plumbing failure causes water to damage flooring, some of the restoration work may be eligible for a claim. However, the policy may exclude the actual pipe repair or limit payment for the cost of reaching the pipe below the slab.
The Cause of the Leak Matters Most
Insurance coverage is usually based less on the word “slab” and more on why the pipe failed. A sudden, accidental pipe break may be handled differently than a leak caused by gradual deterioration.
Common reasons insurers may limit or deny a claim include corrosion, rust, mineral buildup, poor installation, normal aging, repeated leakage, neglect, and long-term seepage. If the carrier determines the leak has been developing slowly, it may argue that the damage was preventable or falls under a maintenance exclusion.
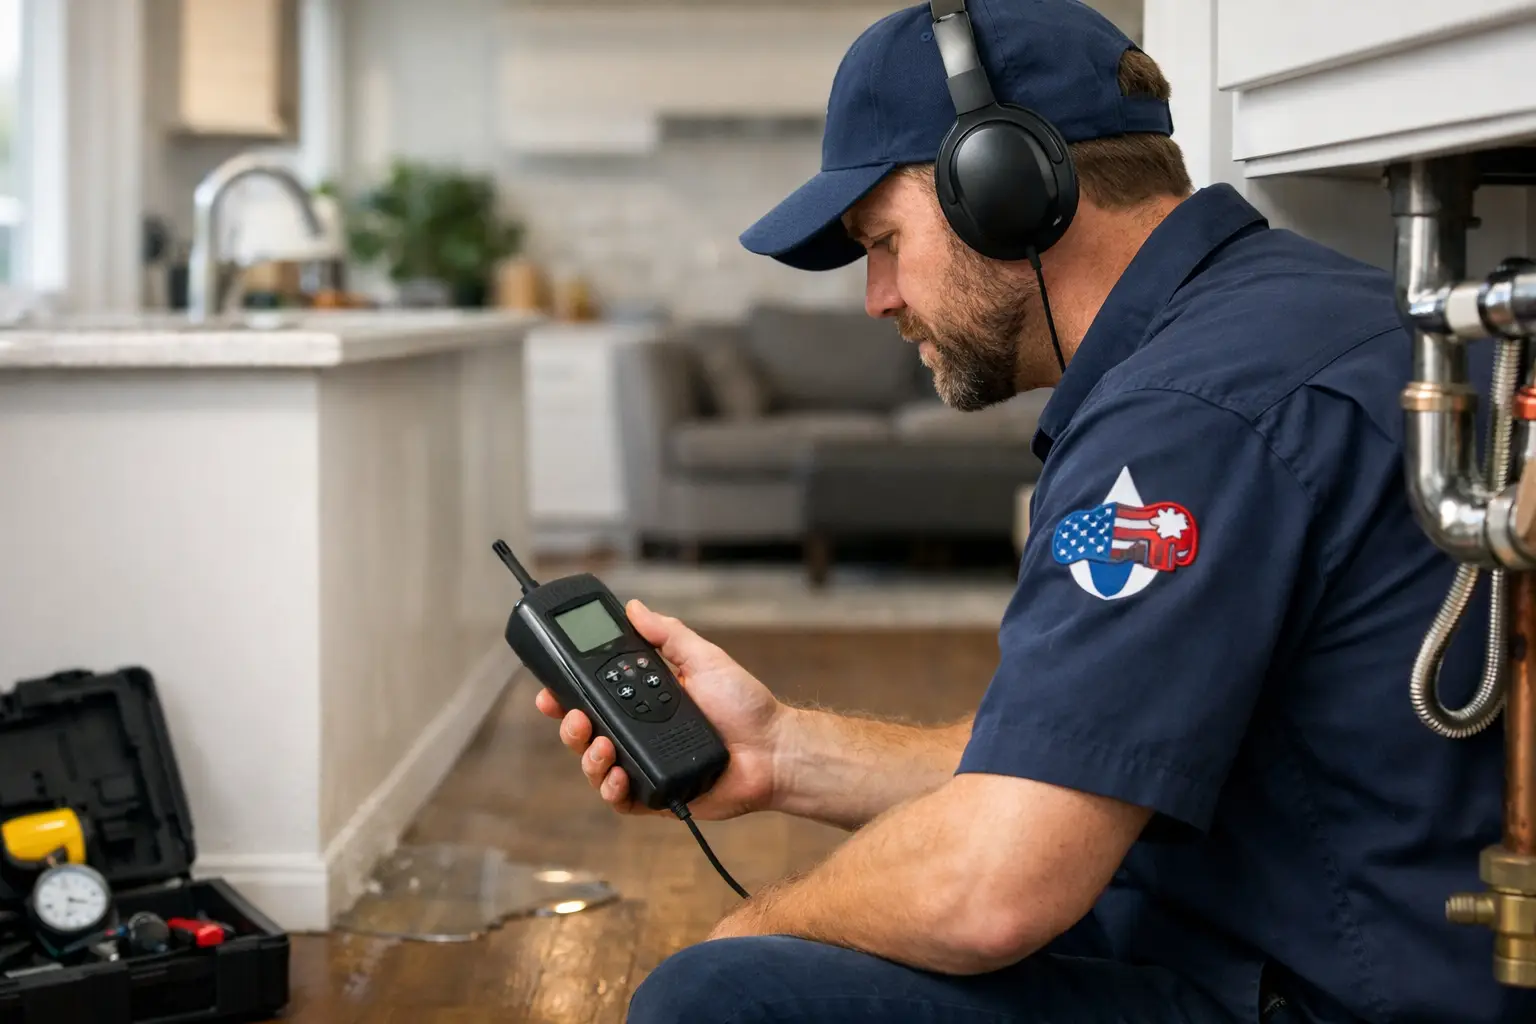
That does not mean you should wait to call for help. Waiting gives a leak more time to damage the home and can make it harder to show when the problem started. Fast professional leak detection helps identify the source, document the condition, and stop active water loss before it becomes a larger restoration project.
Access Costs and Repair Costs Are Different
One of the most confusing parts of a slab leak claim is the difference between access and repair. The pipe may need to be reached by opening a section of flooring and concrete, but the most practical repair may not involve breaking through the slab at all.
Depending on the location and condition of the line, a plumber may recommend a direct repair, a pipe reroute, or replacement of a damaged section. Rerouting can sometimes reduce disruption to the foundation and avoid future trouble in an aging line. It can also cost more upfront than a simple spot repair, especially if multiple fixtures must be reconnected.
Your policy may cover some access-related damage if it is necessary to reach a covered plumbing failure. It may still exclude the cost of replacing the worn-out pipe itself. Some policies offer optional endorsements for hidden water damage, service line issues, or water backup, but those endorsements have their own limits and exclusions.
Before approving work based on an insurance assumption, ask your adjuster direct questions: Does the policy cover damage caused by the leak? Does it cover opening the slab or floor to access the line? Does it cover restoration after the plumbing repair? Is leak detection included? What deductible applies?
Signs You May Have a Slab Leak
You do not need to see water pooling in a room for a slab leak to be serious. Pay attention to changes that do not have an obvious explanation, especially in homes with older plumbing or a history of pipe repairs.
Possible warning signs include:
- A higher-than-normal water bill without increased household water use
- The sound of running water when fixtures and appliances are off
- Warm or damp areas on a floor
- Cracks in flooring, unexplained moisture, or warped materials
- Low water pressure or frequent need to run the water heater
- Mildew odors, damp carpet, or moisture near walls and baseboards
These symptoms can also come from other plumbing problems, which is why professional testing matters. A qualified plumber can isolate the issue and determine whether the leak is in a pressurized water line, a drain line, or another part of the plumbing system.
What to Do Before Filing a Claim
If you suspect a slab leak, take action to limit damage first. Shut off the main water supply if water is actively entering the home or if the leak appears severe. If you are unsure where the shutoff is located, avoid delaying the service call while trying to diagnose the problem yourself.
Next, document what you can. Take clear photos of wet floors, damaged finishes, visible cracks, affected belongings, and water meter readings. Keep copies of high water bills and note when you first noticed the issue. This information can be useful if you file a claim.
Then schedule professional leak detection and repair. An accurate diagnosis gives you practical repair options and helps you communicate clearly with your insurer. In Menifee, Murrieta, Temecula, and nearby communities, American Plumbing Service can locate hidden leaks, explain the recommended repair, and provide a straightforward estimate before work begins.
Avoid authorizing broad demolition before understanding the source of the leak, unless there is an immediate safety or water-damage emergency. A targeted approach can reduce disruption and prevent unnecessary repair costs. At the same time, do not postpone needed repairs while waiting for an insurer to make a coverage decision. Continued leakage can create more damage and may complicate the claim.
Will Insurance Pay for Floor and Wall Repairs?
It may, but only when the damage results from a covered event and the claim exceeds your deductible. Flooring, drywall, baseboards, cabinets, and paint can be expensive to restore after a slab leak. Even when water damage is covered, insurers may apply limits based on the type, age, and condition of the materials.
For example, an insurer may pay for comparable replacement materials rather than a full upgrade. If matching a discontinued floor requires replacing a larger area, that decision can depend on policy language and the adjuster’s assessment. Ask how the carrier handles matching materials before making restoration choices.
Keep in mind that homeowners insurance is not a home warranty or maintenance plan. Its purpose is generally to help with qualifying accidental losses, not to pay for every aging pipe or plumbing upgrade. A clear inspection report and fast repair can still protect your home, whether the claim is approved in full, approved in part, or paid out of pocket.
Questions to Ask Your Insurance Agent Before Trouble Starts
The best time to understand your policy is before water appears on the floor. Review your declarations page and ask whether your policy includes hidden water damage protection, water backup coverage, service line coverage, or any exclusions related to plumbing beneath the foundation.
Also ask whether your policy uses actual cash value or replacement cost for damaged finishes, and confirm your deductible. A higher deductible can lower premiums but may make a small slab leak claim less worthwhile. For homeowners with older homes, it is worth reviewing these details at renewal rather than finding out after a pipe fails.
A slab leak is not a problem to watch for another week. The sooner the source is found and repaired, the better your chances of limiting damage, controlling repair costs, and giving your insurance carrier the documentation it needs to review the claim fairly.